A project that makes a profit on paper can still run out of money halfway, because costs are paid first and progress payments arrive later. A project cash flow shows when money comes in, when it goes out, and whether the cash balance is enough every week or month.
Money in and money out
| Money in | Money out |
|---|---|
| Down payment from the client | Materials and tools |
| Progress payments | Crew advances and labour-contract payments |
| Retention released after the maintenance period | Supplier bills when due |
| Buyer payments (mortgage or cash) | Staff wages and site office costs |
How much cash a progress payment really brings in
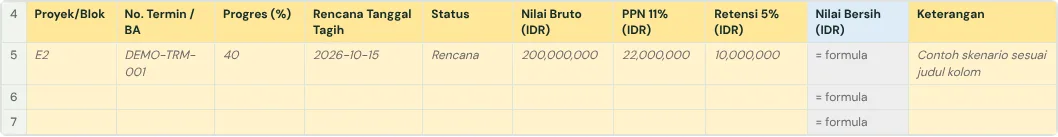
The amount billed is not the cash received. Each payment is usually reduced by the down payment instalment, retention and the final income tax on construction services. An example for a Rp1 billion contract with a 20% down payment and 5% retention; use the percentages in your own contract:
| Item | Amount |
|---|---|
| Progress payment 20% (before VAT) | Rp200,000,000 |
| Down payment repayment (20% of the payment) | minus Rp40,000,000 |
| Retention 5% | minus Rp10,000,000 |
| Final income tax 2.65% (medium qualification, PP 9/2022) | minus Rp5,300,000 |
| Cash received (VAT billed and paid over separately) | Rp144,700,000 |
Use this net figure in the cash flow, not the billed amount. The final tax rate depends on the business qualification (1.75%, 2.65% or 4%); confirm it with your tax adviser. Retention can also be replaced by a bank or insurance maintenance guarantee so the payment is made in full, which helps cash flow.
How to build a project cash flow
- Start from today’s cash and bank balances, per account.
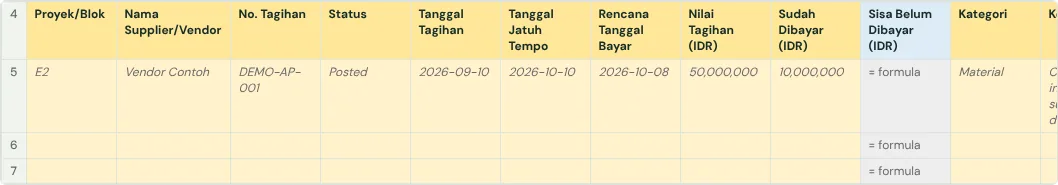
- List money coming in: unpaid invoices and progress payments still to bill, with expected dates.
- List money going out: supplier bills by due date, unbilled purchase orders, wages and regular costs.
- Lay it out per week or month: opening balance + in − out = closing balance.
- Mark periods below your minimum cash balance, then reschedule payments or bill sooner.
- Take the payment dates from the S-curve: when planned progress reaches each billing point, plus the client’s payment delay.
- Update it every week for the next 13 weeks, so a shortfall shows up three months ahead.
Common mistakes
- Treating a progress payment as cash when it is billed, though clients can pay weeks later.
- Counting retention as available money before the maintenance period ends.
- Counting petty cash top-ups as costs, so costs are counted twice.
- No minimum cash balance, so a shortfall is only noticed when it happens.
The full guide is in How to create a construction finance report in Google Sheets. It has a free template (Excel or Google Sheets) and a checker that reads your own workbook.
Ready to use the Komander agents on your projects?
When your workbook is complete, apply for a pilot: we help connect your project data to the Finance, Cost and Scheduler agents and review the first reports with you.
Send to melwani@komander.ai. Your workbook check result is included when there is one; the workbook itself is not sent.
Common questions
What is a construction project cash flow?
A plan and record of when money comes in and goes out on a project, showing whether the cash balance is enough in each period.
What is the difference between cash flow and profit?
Profit looks at total income minus total cost. Cash flow looks at timing: a profitable project can still run short of cash when payments arrive late.
How do I set a minimum cash balance?
Usually a few weeks of regular spending, for example two weeks of wages and supplier bills, so work continues if a payment is late.
Is retention money coming in?
Yes, but on its release date after the maintenance period, not when the progress payment is billed.
References
- Kemenkeu DJPb: Retensi Bukan Pemeliharaan (Indonesian): 5% retention or a maintenance guarantee
- DDTCNews: final income tax rates for construction services (Indonesian): rates under PP 9/2022
- Wiss: Cash Flow Management for Construction Contractors: retention and a 13-week forecast